Flood insurance for Coastal Georgia
Flood insurance for life on the Georgia coast.
Clear guidance for homes, condos, rentals, and commercial property—from Brunswick to Savannah and the barrier islands between.
Start with the property
What are you insuring?
The building and how you use it shape the questions worth asking. Choose the closest match to see where to begin.
A useful place to begin
Primary residence
Start with building and belongings coverage, your foundation, lowest floor, and any current elevation or policy documents.
Explore this pathGet a Free Flood Insurance Quote
Start with understanding
Know the options.
Read what changes.
NFIP and private flood insurance can differ in limits, deductibles, waiting periods, exclusions, and underwriting. The best comparison is the one tied to the actual property.
A clearer path
Four steps from property to protection.
- 01
Tell us about your property
Share the address and a few useful details.
- 02
Explore coverage options
Review available limits, deductibles, and forms.
- 03
Receive your quote
Get pricing based on verified insurer availability.
- 04
Choose your protection
Confirm terms, exclusions, effective date, and next steps.
Two paths worth comparing
NFIP and private flood insurance.
Neither label tells the whole story. Compare the policy that is actually available for your address.
See the full comparisonStandard federal form
Varies by insurer
Up to $250,000
May offer higher limits
30 days; exceptions apply
Varies by insurer
Participating communities
Property-specific underwriting
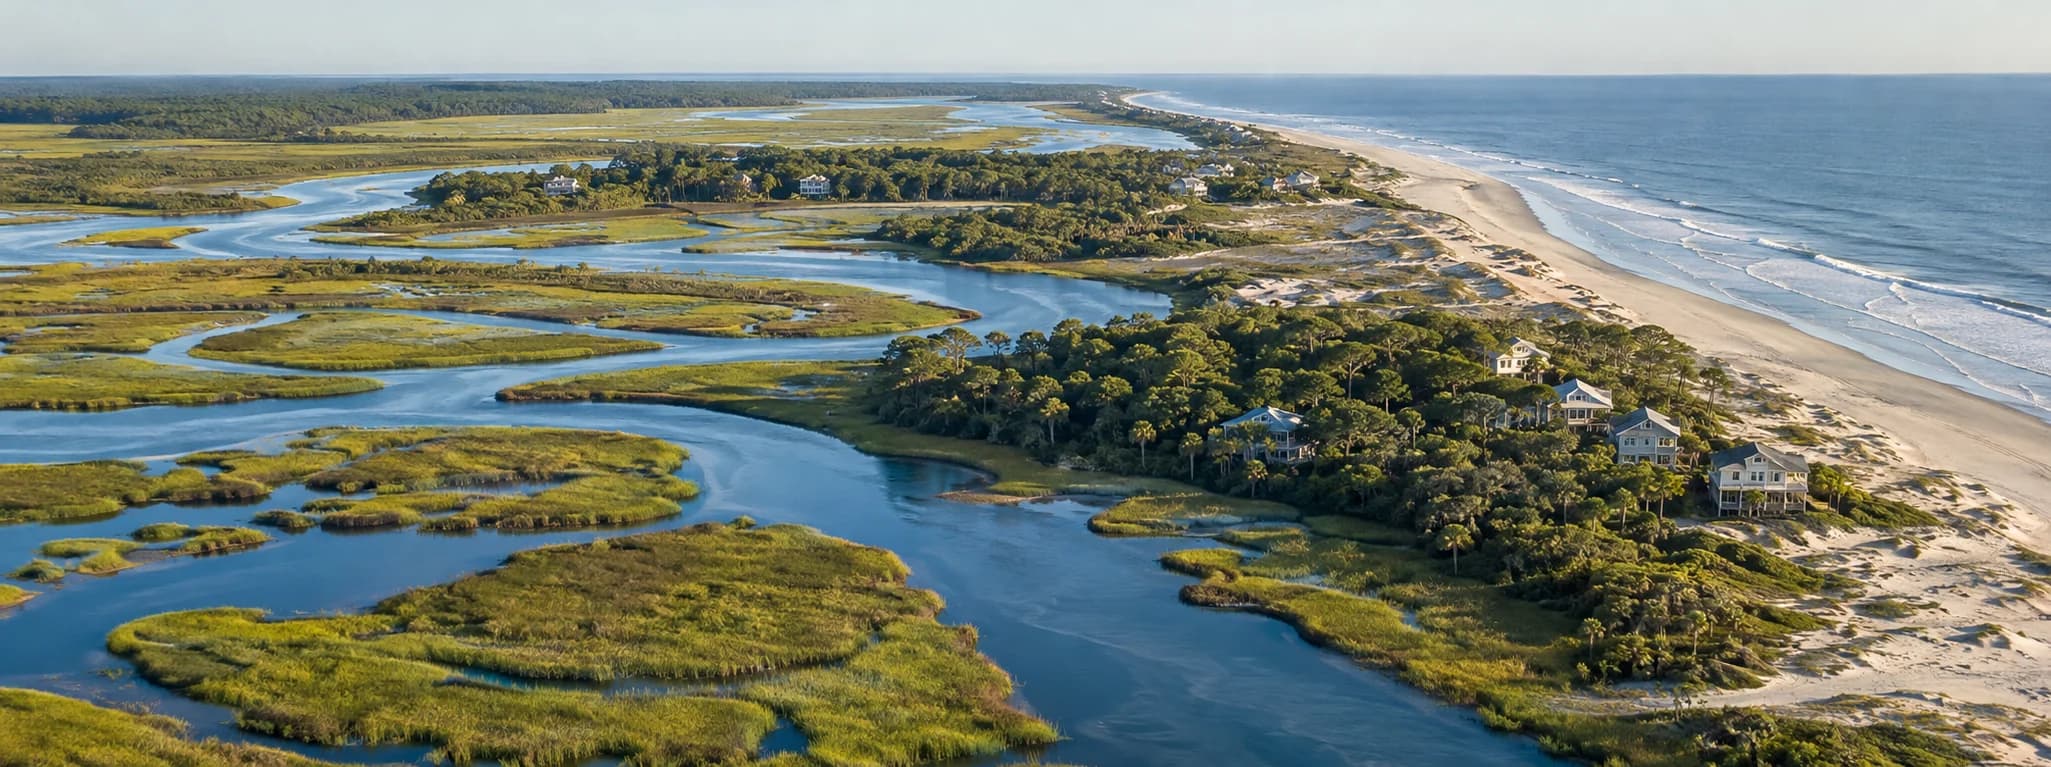
Coastal Georgia, property by property
Local context. Address-level answers.
From Glynn County’s islands and marshes to the varied properties of Savannah and Chatham County, useful guidance starts with current maps and the building itself.
Plain answers first
Good questions.
Clear next steps.
Flood insurance has technical language. The explanation should not.
Do I need flood insurance near the coast?
A lender may require flood insurance for some mortgages in a Special Flood Hazard Area. Even when it is not required, the decision can still be worth reviewing because mapped zones do not mean zero risk outside high-risk areas.
What can flood insurance cover?
Depending on the policy, eligible direct physical flood damage to the building and belongings may be covered. Building and contents limits, deductibles, and exclusions should be reviewed separately.
How is a flood insurance quote determined?
The address, construction, occupancy, elevation, replacement cost, coverage selections, loss information, and insurer underwriting can all matter. A flood zone is only one input.
When would my coverage begin?
NFIP policies generally have a 30-day waiting period, with defined exceptions. Private-policy waiting periods vary. The effective date must be confirmed in writing.
A straightforward process
Getting a flood insurance quote shouldn’t be complicated.
Tell us what you know about the property. We’ll help fill in the gaps, explain available options, and make the next step clear.
Get a Free Flood Insurance Quote